The Metro Phoenix Housing Market Went from Bad to Worse
Metro Phoenix Housing Market: October 2026 Sets Another Record Low for Supply and Demand
The Metro Phoenix housing market continues to weaken, and the October numbers are particularly concerning.
At the beginning of October, the Supply/Demand Ratio had fallen to 26.26%, the lowest level since I began tracking this indicator.
One month later, it has fallen even further.
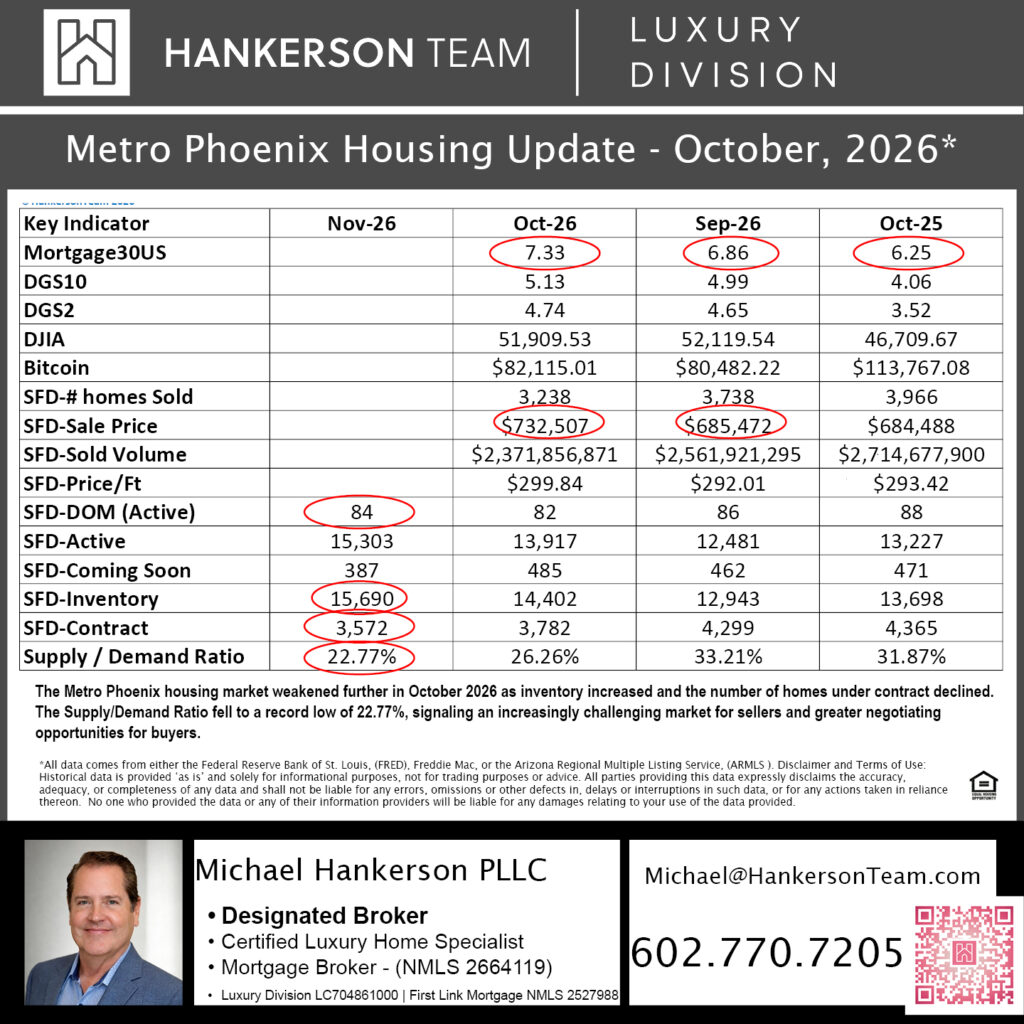
As of November 1, the Supply/Demand Ratio stands at 22.77%, another record low.
This is not simply a case of more homes coming onto the market. Inventory is increasing while the number of homes under contract is declining. Both sides of the equation are moving in the wrong direction.
More Homes for Sale, Fewer Buyers Under Contract
On October 1, Metro Phoenix had 14,402 single-family detached homes in inventory, with 3,782 under contract.
By November 1, inventory had increased to 15,690 homes, while the number under contract had fallen to 3,572.
That represents an increase of 1,288 homes in inventory, or approximately 8.9%, while the number under contract declined by 5.6%.
Looking back just two months makes the change even more significant.
On September 1, inventory was 12,943 homes, with 4,299 under contract. The Supply/Demand Ratio was 33.21%.
In just 60 days, inventory increased by 2,747 homes, or 21.2%, while the number under contract declined by 727 homes, or 16.9%.
The Supply/Demand Ratio fell from 33.21% to 22.77%.
Under the benchmarks I use for this report, anything below 30% represents an extreme buyer’s market. We crossed that threshold in October and have moved substantially further into that territory.
More homes are competing for fewer buyers who are actually entering contracts.
October Home Sales Were Also Weak
October recorded just 3,238 completed single-family detached home sales in Maricopa County.
That compares with 3,738 sales in September and 3,966 in October 2025.
Sales declined approximately 13.4% from September and 18.4% compared with the previous year.
The number of sales matters because it shows how many transactions actually closed. But closings are generally the result of contracts negotiated weeks earlier.
That makes the current inventory and under-contract numbers particularly important. They provide a more immediate picture of market activity than closed sales alone.
And those numbers have continued to deteriorate.
Total dollar volume sold also declined, from approximately $2.56 billion in September to $2.37 billion in October, a decrease of 7.4%.
But Home Sale Prices Actually Increased
Here is where the October report gets interesting.
Despite fewer sales and a worsening Supply/Demand Ratio, the average sale price increased.
The average single-family detached home sold for $732,507 in October, compared with $685,472 in September.
That is an increase of approximately 6.9%.
The average price per square foot also increased, from $292.01 in September to $299.84 in October, an increase of approximately 2.7%.
Compared with October 2025, the average sale price increased approximately 7%, while the average price per square foot increased approximately 2.2%.
On the surface, these numbers suggest home prices are holding up remarkably well.
But there is an important distinction between the prices of homes that sold and the market conditions facing homes that have not sold.
The average sale price measures the homes that actually closed during October. It does not tell us that every home in Metro Phoenix increased in value by nearly 7% in one month.
Changes in the types and prices of homes selling can affect the average.
Meanwhile, the number of homes available for sale continues to increase, and the number going under contract continues to decline.
These are two different views of the market, and both deserve attention.
Sellers Face Increasing Competition
For homeowners considering selling, the growing inventory and declining number of contracts should be taken seriously.
A home is not competing with what sold three months ago. It is competing with the other homes available to buyers today.
With 15,690 homes in inventory and only 3,572 under contract, buyers have considerably more choices than they did just two months ago.
Active days on market increased from 82 to 84 days during October. That remains well above the approximately 60-day historical benchmark I use.
This does not mean every seller needs to reduce their asking price. It does mean that pricing, condition, presentation, and financing terms become increasingly important when buyers have more alternatives.
The price a seller wants and the price a buyer is willing and able to pay are not necessarily the same.
Buyers Have More Options, But Payments Still Matter
For buyers, these conditions may create opportunities that were much harder to find when inventory was limited and sellers had multiple competing offers.
More homes available for sale can mean more choices, more time to compare properties, and potentially greater flexibility in negotiating price and terms.
But a buyer’s decision should not be based entirely on the asking price or the quoted mortgage interest rate.
The mortgage-rate benchmark in the October report increased from 6.86% in September to 7.33% in October.
For many buyers, the more important consideration is the monthly payment they can comfortably afford.
Rather than beginning with a specific interest rate and accepting whatever payment results, buyers can work backward from their desired payment to determine what purchase price and financing terms might make sense.
That may involve negotiating a lower purchase price, requesting seller concessions toward closing costs, or evaluating whether an interest-rate buydown is financially worthwhile.
The objective is to structure a purchase around an affordable payment, not simply focus on the interest rate.
Of course, financing options and concessions depend on the particular transaction, loan program, and borrower qualifications.
What the October Numbers Tell Us
We are seeing a significant disconnect between the prices of homes that are successfully closing and the weakening market conditions reflected in inventory and contracts.
Average sale prices increased in October, but fewer homes sold.
Inventory continued to grow, while the number of homes under contract fell.
And the Supply/Demand Ratio reached another record low at 22.77%.
That does not establish that home prices are about to fall dramatically. It does, however, show that the balance between available homes and current contract activity has deteriorated significantly.
For sellers, the challenge is competing for a smaller pool of buyers relative to the number of available homes.
For buyers, the opportunity is having more choices and potentially greater negotiating flexibility.
The most important number in this month’s report is not the average sale price. It is the continuing decline in the Supply/Demand Ratio.
That is where the greatest change in the Metro Phoenix housing market is taking place.
Market data covers single-family detached homes in the Maricopa County ARMLS dataset. It does not include condominiums, townhomes, or other property types.
All data comes from either the Federal Reserve Bank of St. Louis, (FRED), Freddie Mac, or the Arizona Regional Multiple Listing Service, (ARMLS). Historical data is provided ‘as is’ and solely for informational purposes, not for trading purposes or advice. All parties providing this data expressly disclaims the accuracy, adequacy, or completeness of any data and shall not be liable for any errors, omissions or other defects in, delays or interruptions in such data, or for any actions taken in reliance thereon. No one who provided the data or any of their information providers will be liable for any damages relating to your use of the data provided.